
The Mechanics of Negotiation — Weaponizing Seller Equity
The mainstream media obsesses over list prices. They lead the average buyer to believe that the sticker price is the definitive cost of acquisition, which results in many home buyers viewing the transaction through a retail-minded lens.
But real estate is not a fixed-price market. It is an inefficient, highly negotiable system where one of the most powerful micro levers is often hidden from the headline data: Seller Concessions.
If you view the transaction strictly as a binary negotiation over the final sale price, you are leaving massive amounts of capital on the table. A First Principles buyer understands how to weaponize the seller’s equity to structurally engineer a more profitable acquisition.
The Mathematical Reality: A Structural Shift
With a peak 2021-perspective still lingering, many buyers believe they still don’t have much leverage in today’s environment. The mathematical reality tells a different story. There is an upward trajectory of buyers successfully extracting capital from sellers year after year:
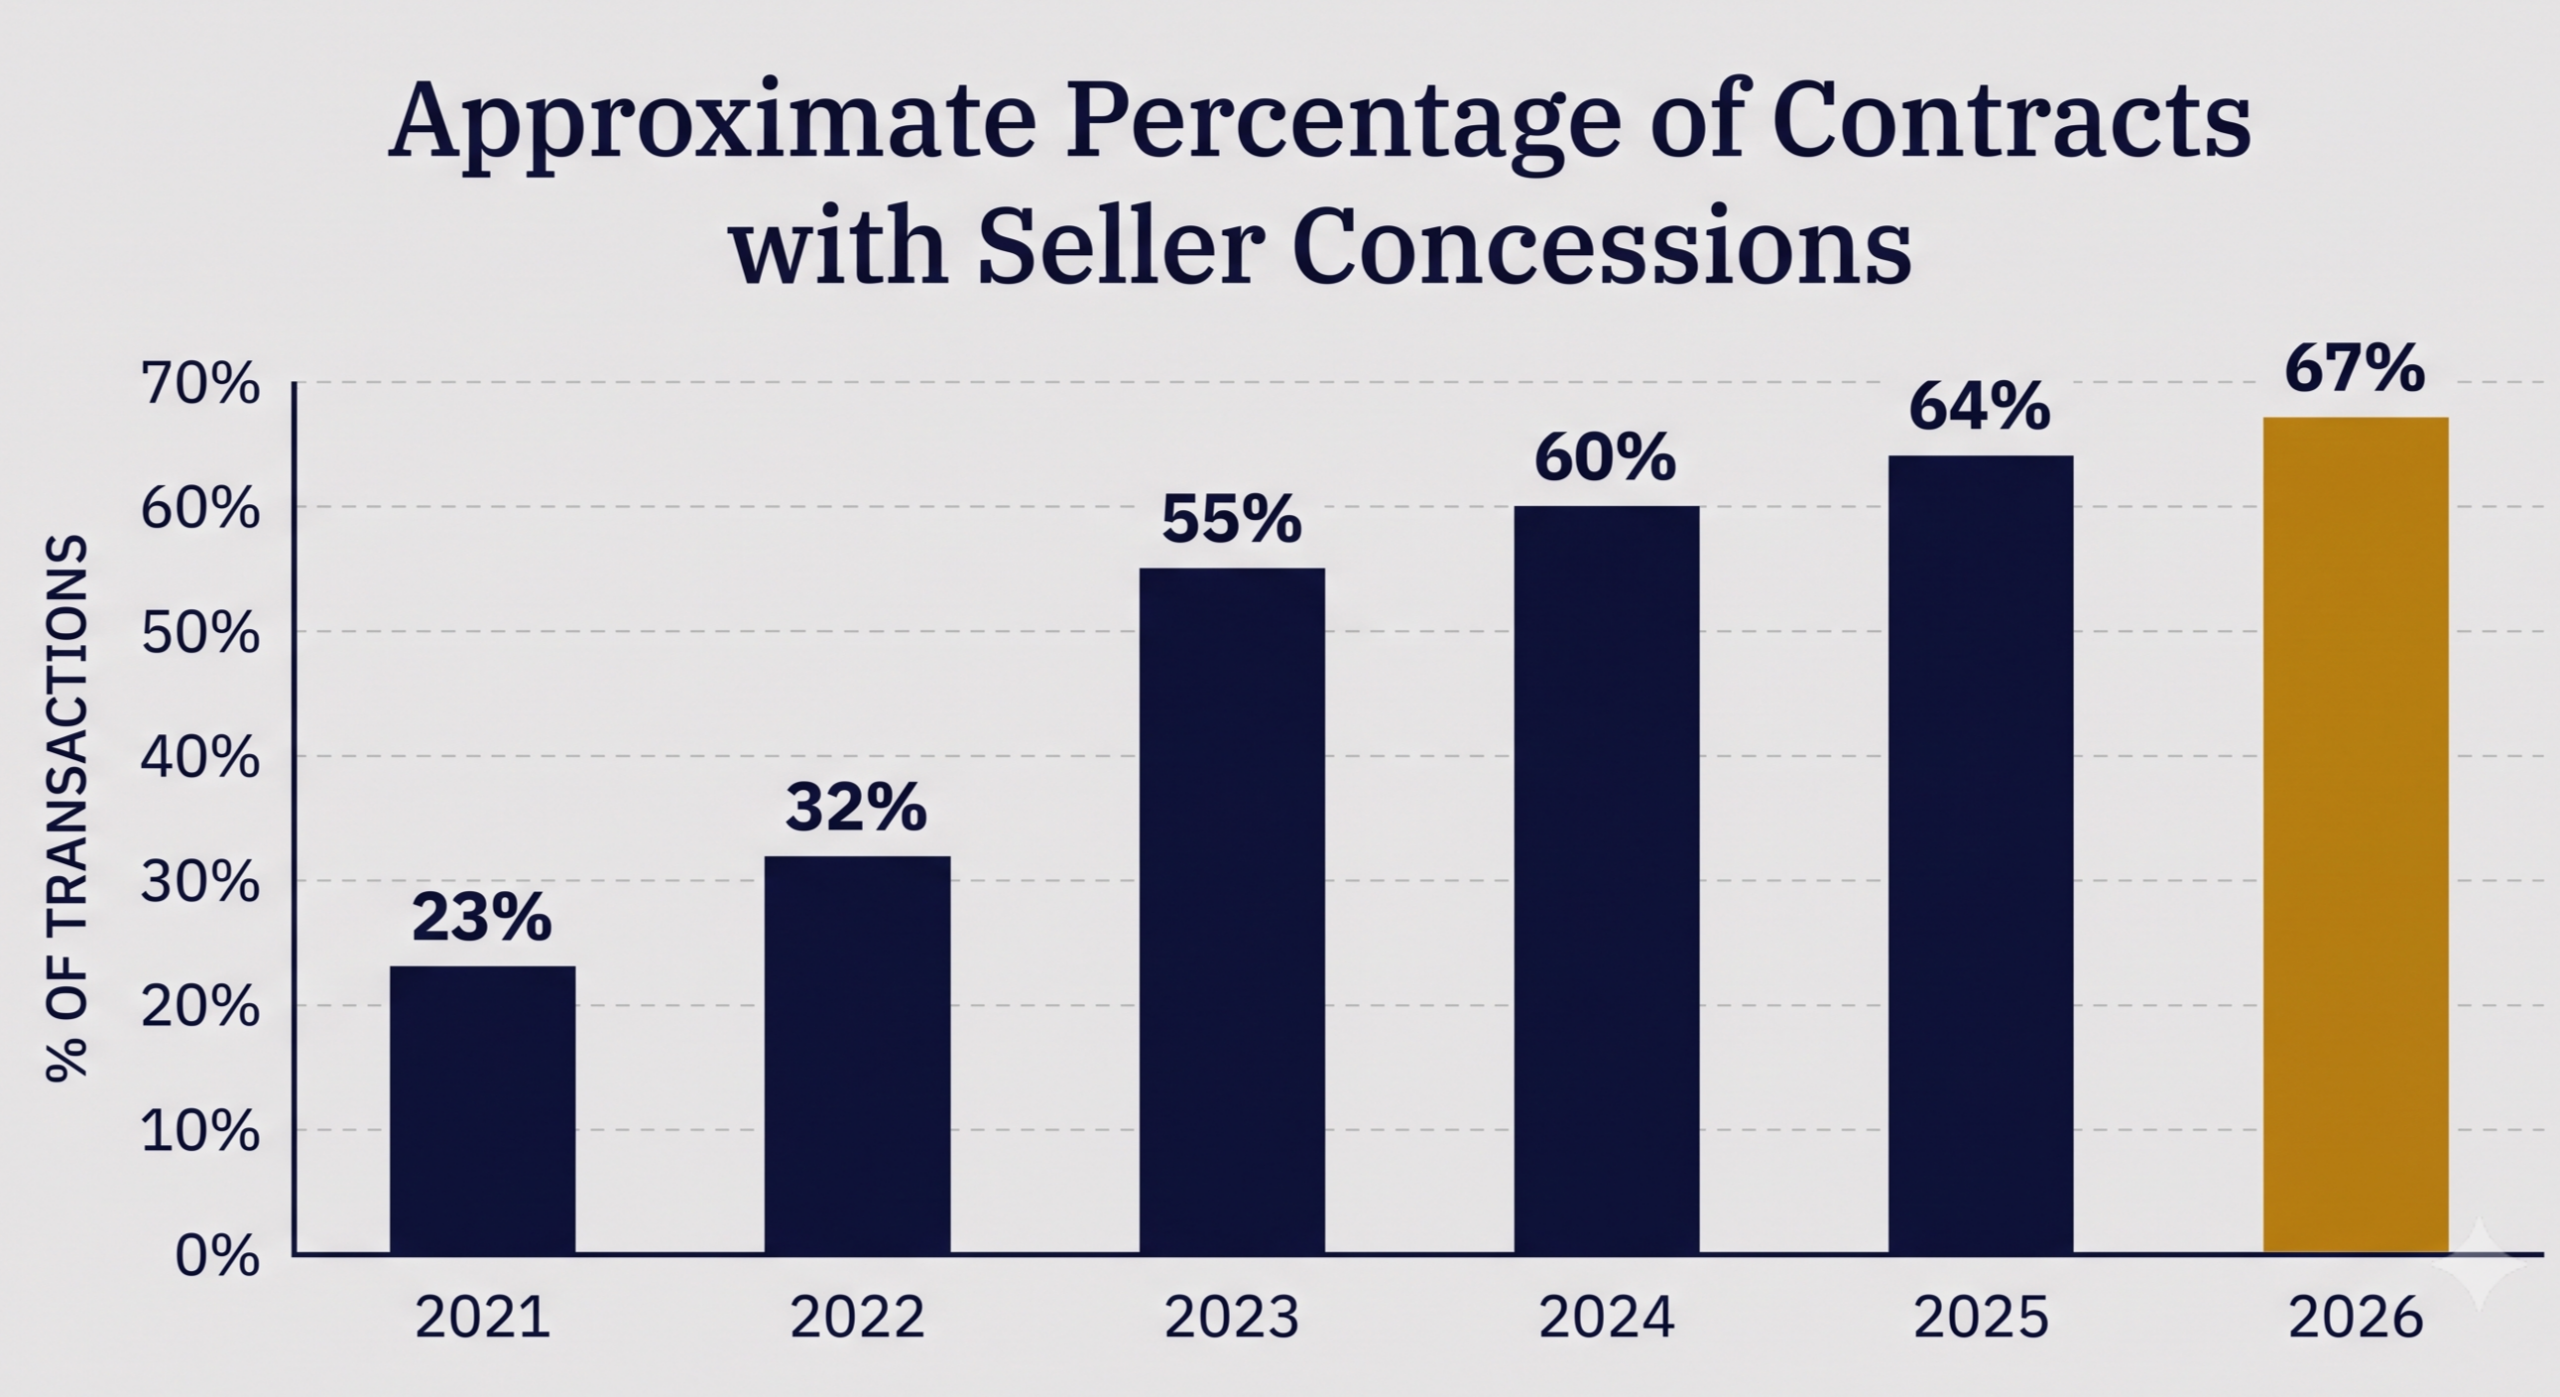
This is a structural normalization of how deals are funded. As of 2026, data shows that 67% of all real estate contracts involve the seller offering a portion of their gross equity to offset the buyer’s financial friction. If your model doesn’t account for this bargaining tool, your execution strategy is incomplete.
Deconstructing the Concession: What Is It?
In conventional terms, a seller concession is simply a seller agreeing to pay for some of your costs.
In a First Principles model, a seller concession is a contractual transfer of capital from the seller’s net proceeds directly to the buyer’s balance sheet at the time of closing. The seller does not write you a personal check; instead, the Title Company systematically reroutes a percentage of the seller’s profit to absorb your transactional friction.

The Regulatory Boundaries Before deploying a concession strategy, you must understand the regulatory physics. A seller concession cannot, under any circumstances, be used to fund your minimum down payment obligation. They are strictly designated to neutralize the actual friction of the transaction: standard closing costs, prepaid escrow balances, discount points, etc. However, this allows capital set aside for those items to be reallocated towards the down payment.
For conventional loans, Fannie Mae and Freddie Mac enforce strict federal limitations on these transfers, formally classified as Seller Interested Party Contributions (IPCs). Your ability to extract capital is capped based on your Loan-to-Value (LTV) ratio:

The Three Vectors of Seller Concessions
Uninformed buyers who successfully negotiate a concession usually apply it directly to the purchase price—an ego-driven move that barely impacts their monthly outlay. Rigorous financial models deploy this capital through three highly specific vectors to maximize ROI:
- Closing Cost Subsidies: By directing seller concessions toward transactional friction—like title insurance, origination fees, and escrow accounts—you absorb the shock using someone else’s money. This preserves your personal cash reserves for emergency buffers or immediate asset updates.
- Interest Rate Buydowns: Instead of dropping the purchase price, you deploy the seller’s capital to purchase discount points or execute a 2-1 Buydown. By structurally lowering your interest rate, you insulate your debt profile against macroeconomic volatility and engineer higher monthly cash flow.
- Repair Credits: When due diligence reveals aging systems (like a failing HVAC), you do not ask the seller to fix it. Sellers apply bandages, not cures. Instead, you negotiate a credit, take the seller’s capital at closing, and deposit it directly into your CapEx Reserve account to fund the replacement on your own timeline.
The $400,000 Acquisition: Engineering the Baseline
Suppose you are acquiring a $400,000 home and bringing a 10% down payment ($40,000). Because you are putting 10% down, you are legally authorized to negotiate up to a 6% concession, which equates to a massive $24,000 ceiling.
Average mortgage closing costs typically range between 2% and 5% of a home’s purchase price. For this model, let’s assume your total transactional friction sits right at 3%, and you successfully negotiate a $12,000 seller concession.
Here is how the seller’s equity could absorb your capital friction:
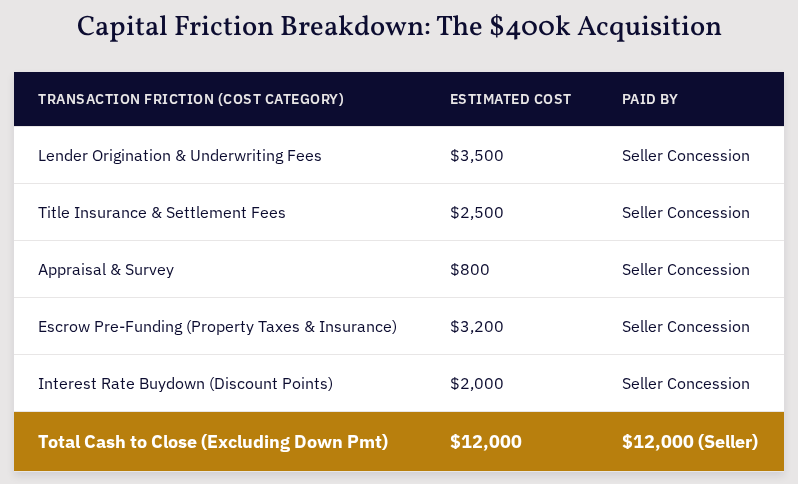
The Strategic Impact By successfully routing the seller’s $12,000 concession directly into these distinct line items, you shift the burden entirely. The most dangerous time for a homebuyer is the day after closing when cash reserves are drained. By utilizing the seller’s equity, that $12,000 stays in your bank account. Furthermore, by allocating $2,000 to purchase discount points, you utilize their equity to permanently compress your long-term cost of borrowing.
Are You Average?
The headlines want you to believe you are a victim of a rigid, unaffordable system dominated by high prices. The reality is that the system is incredibly malleable if you know how to negotiate the underlying math rather than just the sticker price. If you aren’t “average,” why fixate on the average headline?
Apply this methodology to your specific situation here: FPP Analytical Tools
Comments