
Engineering the Year-Two Shock — The Mechanics of Uncapping
The mainstream media, retail lenders, and popular real estate portals sell buyers on a dangerously simple budgeting strategy: look at the public record, find what the current seller is paying in property taxes, and plug that exact number into your monthly payment model.
To the average homebuyer, this seems perfectly logical. It is public data, so it must be accurate.
However, this assumption is a fatal structural flaw. Real estate taxes do not transfer laterally. The seller’s tax bill is heavily subsidized by time, and the moment the deed transfers, that subsidy is permanently destroyed. Relying on historical tax data guarantees that your financial model will fail exactly twelve months after closing.
Welcome to the Property Tax Reset.
The Physics of the Cap
To understand the impending capital friction, you must understand how municipalities assess value.
In most states, local governments place a strict, legal cap on how much a homeowner’s taxable value can increase each year. Often, this is tied to the rate of inflation or a hard ceiling (e.g., 3% to 5%), regardless of how rapidly the actual market value of the property is appreciating.
If a seller has owned a property for ten years, their home’s market value may have doubled, but their taxable value has been artificially suppressed by the municipal cap. They are paying taxes on a phantom, discounted value that no longer exists in reality.

The Uncapping Event
One of the most unplanned impacts on a buyer’s liquidity is the execution of the deed transfer.
When you purchase the asset, the municipality legally strips away the historical cap. The property is “uncapped,” and the local assessor resets the taxable value to reflect the new, current market reality—your acquisition price.
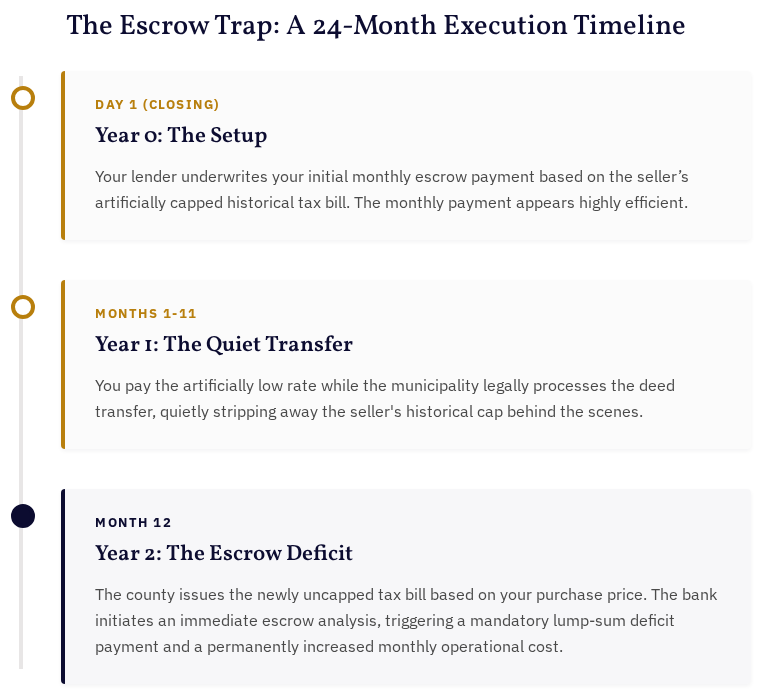
The structural danger lies in the timeline. Your lender calculates your Year-One escrow requirements based on the seller’s old, capped tax bill. Your monthly payment looks highly efficient. But when Year Two arrives, the county issues the newly uncapped tax bill.
This triggers a mathematical phenomenon known as an Escrow Shortage, delivering a brutal, two-pronged attack on your cash flow:
- The Payment Spike: Your baseline monthly payment permanently adjusts upward to absorb the true tax liability.
- The Escrow Deficit: Because your Year-One escrow account was underfunded, the bank requires an immediate, lump-sum capital injection to cover the negative balance.
The Operational Equation: Calculating True Liability
A rigorous model does not wait for the county to dictate the terms; it forecasts the friction before capital is deployed. To calculate your true post-acquisition tax burden, you must discard the historical data and engineer the operational equation based on your acquisition cost.

The $400,000 Acquisition: Modeling the Shock
Let’s apply mathematics to a standard acquisition. You are purchasing a $400,000 home from a seller who bought the asset in 2014 for $200,000. The local effective tax rate is exactly 1.5%.
Here is the difference between the naive media model and the First Principles reality:

If your household budgeted strictly based on the Year-One baseline, the physical reality of a sudden $188 monthly payment spike—combined with a mandatory $2,256 lump-sum deficit payment—will instantly impact the cash reserves you earmarked for maintenance, CapEx, or your emergency safety net.
The Bottom Line
A financial model is only as powerful as the physics it accounts for. Using a seller’s historical tax data is not a baseline; it is a mathematical illusion. A First Principles buyer entirely ignores the public tax record of the current owner. Instead, they manually model the uncapped tax liability using the target purchase price and pre-fund their own liquidity reserves to absorb the Year-Two shock without compromising their savings.
Are You Average?
The media treats purchasing a home as a static transaction, ignoring the cascading mechanical realities of the municipal tax code. True affordability is not dictated by your first mortgage statement; it is engineered by forecasting your exposure to hidden systemic friction. If you aren’t “average,” why fixate on the average headline?
Apply this methodology to your specific situation here: FPP Analytical Tools
Comments