
The Illusion of Fixed Costs & Mastering the Micro Levers
The media treats buying a house like buying a TV at Best Buy. You look at the sticker price, check your bank account, and decide if you can afford it.
But here’s the reality: real estate is not a retail transaction. It is an imperfect, highly inefficient, and entirely negotiable system. The sticker price and the quoted interest rate are not laws of physics—they are just opening bids.
In “Media to Models 1”, we proved that a single architectural choice could pull your affordability ratio out of a “crisis” and back to a 50-year norm. Now, we are going to look at the capital side.
If you view the transaction strictly as “Purchase Price vs. Interest Rate,” you are playing checkers while the models are playing chess. Welcome to Financial Engineering.
The Setup: Acquiring Your “Friction Capital”
Let’s look at a baseline model. You are buying a $400,000 home. The market rate is sitting at roughly 6.5%. During negotiations—maybe after a tough inspection, or simply because the seller is motivated—you successfully negotiate $10,000 in concessions.
Here is where most buyers execute what we’ll call “The Ego Move.” They take that $10,000 and hack it right off the purchase price.
- The Ego Move ($10k Price Drop): Dropping the loan amount from $360k to $350k saves you a whopping $63 a month.
It feels great to say you “talked them down 10 grand,” but mathematically, it is the least efficient way to deploy capital. Instead of treating that $10,000 as a discount, our models treat it as a tool to permanently alter the structure of your loan.
Here are three ways to engineer a mathematically superior outcome:
Lever 1: The Capital Cost Strategy (Permanent Rate Buydown)
If the interest rate is the “Volatility Monster”, this lever is how you slay it. Keep the purchase price at $400,000, but use the seller’s $10,000 to permanently buy down your interest rate.
By purchasing discount points, you effectively lower the baseline cost of capital from 6.5% to a permanently locked 5.875% for the entire 30-year life of the loan.
If we look at the standard amortization formula for calculating your monthly payment ($M$):
$$M = P left( frac{r(1+r)^n}{(1+r)^n – 1} right)$$
Because the interest rate ($r$) compounds exponentially, attacking the rate yields massive returns compared to attacking the principal ($P$).
- The Result: Instead of saving $63 a month with a price drop, this lever drops your monthly payment by $145. That makes this strategy 2.3 times more impactful than reducing the purchase price. You hit a mathematical break-even on the deployed capital in about 5.6 years, and you’ve structurally insulated yourself from macro market volatility using the seller’s equity. Arguing over the sticker price is an ego trip; arguing over the cost of capital is how you build wealth.

Lever 2: The Time-Shift Strategy (The 2-1 Buydown)
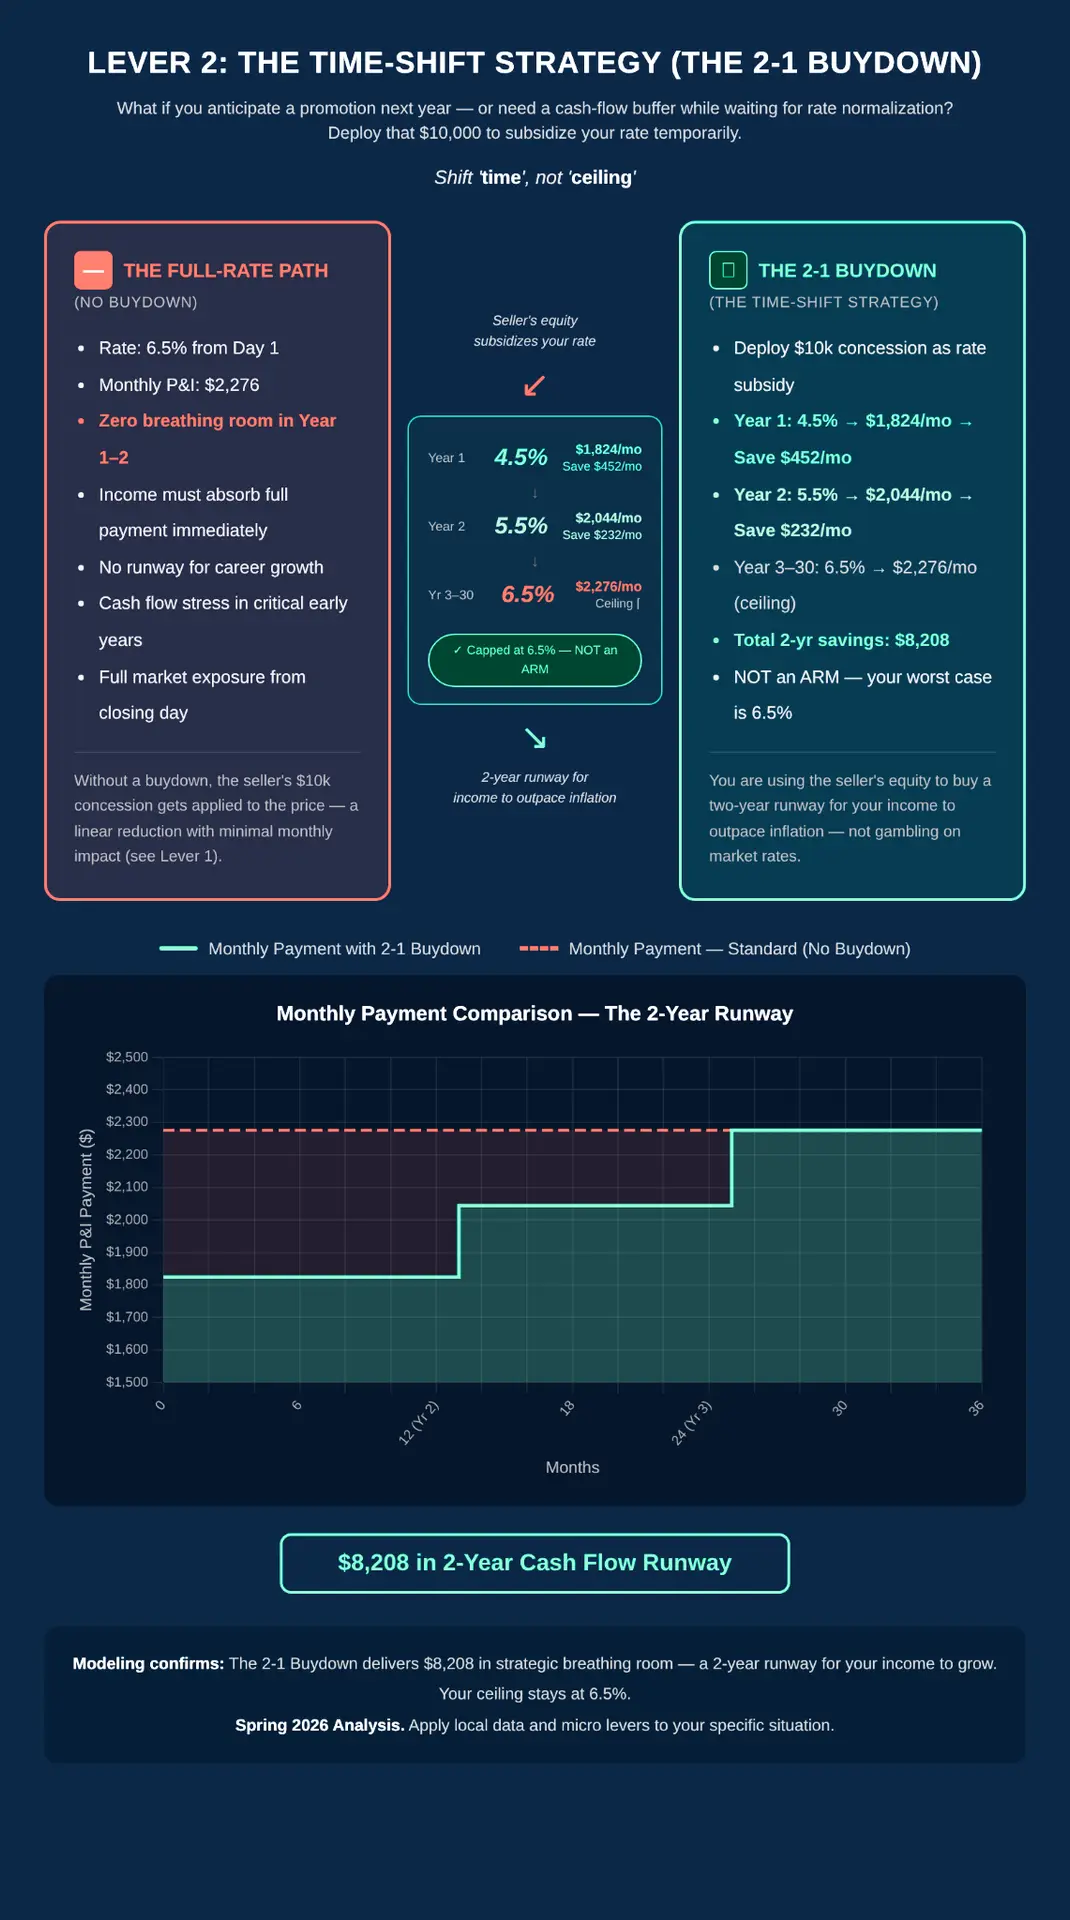
What if you anticipate a promotion next year, or you simply want a heavier cash-flow buffer today while we wait for the Fed’s “structural normalization”? You can deploy that $10,000 to subsidize your rate temporarily.
In a 2-1 Buydown, the seller’s concession pays the difference in interest for the first two years:
- Year 1: Your effective rate is 4.5% (Massive monthly savings).
- Year 2: Your effective rate is 5.5% (Moderate monthly savings).
- Year 3-30: Your rate normalizes at the 6.5% baseline.
This isn’t an Adjustable Rate Mortgage (ARM) where the market dictates your worst-case scenario. Your ceiling is safely capped at 6.5%. You are simply using the seller’s equity to buy yourself a two-year runway for your income to outpace inflation.
Lever 3: The PMI Assassination
Private Mortgage Insurance (PMI) is widely accepted as a mandatory penalty box for buyers who don’t put 20% down. The media treats it as a fixed tax. It is not. The entire PMI system is negotiable, especially if you are putting 10% to 15% down. It is not a rigid law; it is a risk metric assessed by private insurers who want your business.
Instead of accepting a $150 to $200 monthly PMI charge for the next 7 to 10 years, you can use a portion of your $10,000 seller concession to execute a “Single Premium Buyout.”
- The Result: For a fraction of the concession (often $3,000 to $5,000), you buy out the PMI completely at closing. The leftover concession covers your closing costs. You instantly eradicate a monthly friction cost that offers zero tax benefit and builds zero equity.

Are You Average?
The headlines want you to believe you are a victim of a rigid, unaffordable system. The reality is that the system is incredibly malleable if you know which levers to pull. You do not have to wait for the Federal Reserve to save you; you can engineer your own affordability today. If you aren’t “average,” why fixate on the average headline?
Apply local data and micro levers to your specific situation here: https://thefppartners.com/free-analysis-toolkit
Comments